


Millions of children in single-parent households begin life with disadvantages that are not of their making. Rather than asking how public policy can help those children succeed, flourish, and thrive, too much of our political debate begins by asking how to change the adults around them. The policies they propose (e.g., work requirements and marriage enforcement) are often punitive and punish the children who need the most support with the least.
Instead, child policy should begin with children.
Children do not choose whether they are born into a two-parent household, a single-parent household, a military family, a foster family, an immigrant family, a wealthy family, or a family struggling with disability, unemployment, or substance abuse. They should not receive less support because of circumstances beyond their control. That principle should guide every child policy we write.
The American people agree. In a study by Rebecca Kreitzer and Candis Watts Smith that sought to assess which groups Americans believe are most “deserving” of support and assistance, children ranked second only to veterans and ahead of all other groups, including favored populations like seniors, people with disabilities, mothers, and soldiers.1
However, when some think tanks or political commentators look at families, they impose judgment on adults, including single parents, that often ignores some fundamental truths and structural barriers that put those families and their children at a significant disadvantage:
Income is significantly higher in two-earner households.
Women, who are far more likely to be the caregiver in single-parent households, continue to face employment discrimination and salary disparities.
The U.S. does not have a coherent and universal child care policy.
The U.S. is one of the only high-income countries without guaranteed paid family and medical leave.
Compounding these structural problems is a Child Tax Credit that is built to better serve two-earner households, and leaves over 1-in-4 children, or 28%, behind with less than a full credit as a result. This policy punishes low-income families by denying them the credit or only allowing them a partial credit because their parent(s) earn “too little” to receive the full benefit.
Since single-parent households are more likely to be poor, their children are also far more likely to be excluded from the Child Tax Credit. This exclusion is by design.
If Congress truly wanted to help all children succeed, flourish, and thrive, the Child Tax Credit would be designed to compensate for underlying disadvantages rather than magnify them. Instead, current policy does the opposite.
Analysis from Columbia University’s Center on Poverty and Social Policy (CPSP), paired with a policy brief a team of graduating seniors at the University of Maryland School of Public Policy produced for First Focus on Children last semester, makes the mechanism visible.
The Scale of the Problem
According to CPSP, 28% of children under 17 are “left behind” by the Child Tax Credit under the so-called “One Big Beautiful Bill” (OBBB) — either ineligible or only partially eligible because their family’s income is too low to qualify for and claim the full credit. This is up from 25% left behind before the passage of OBBB.2
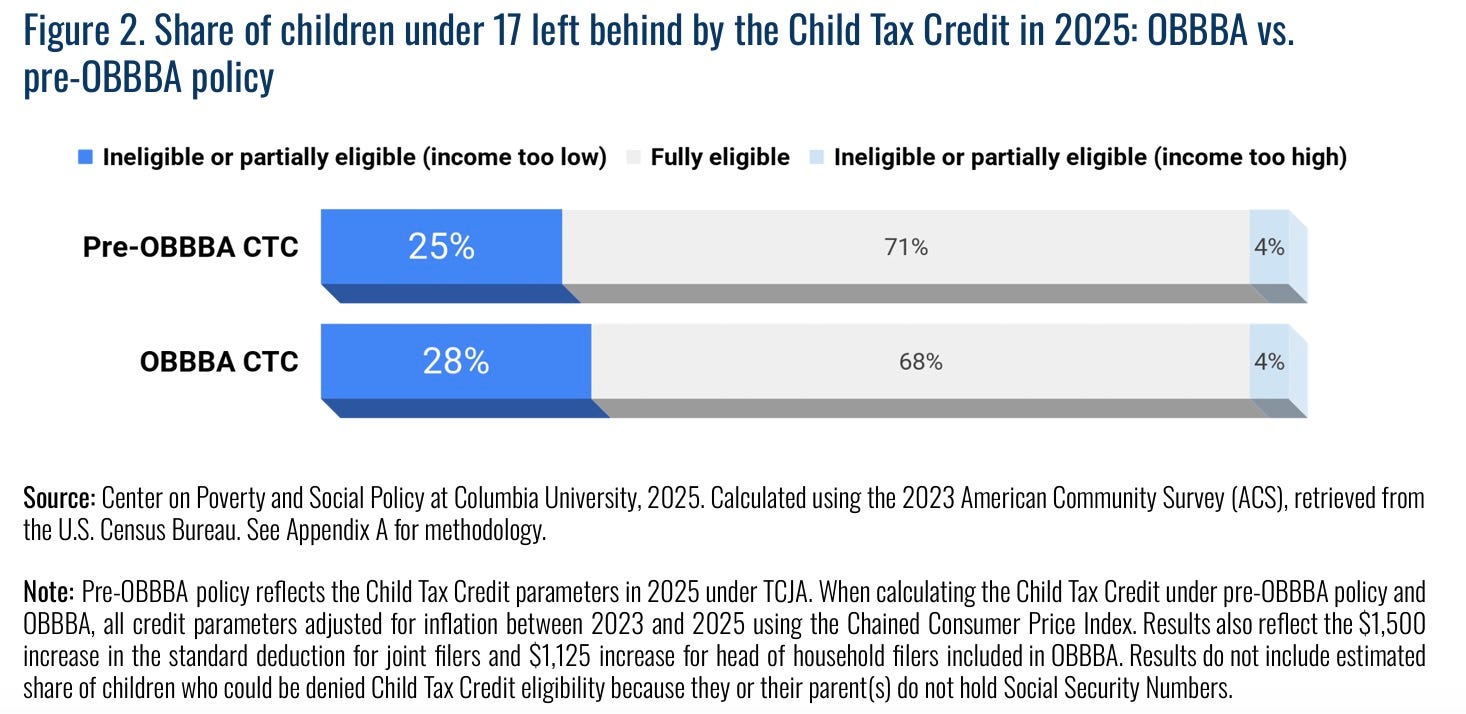
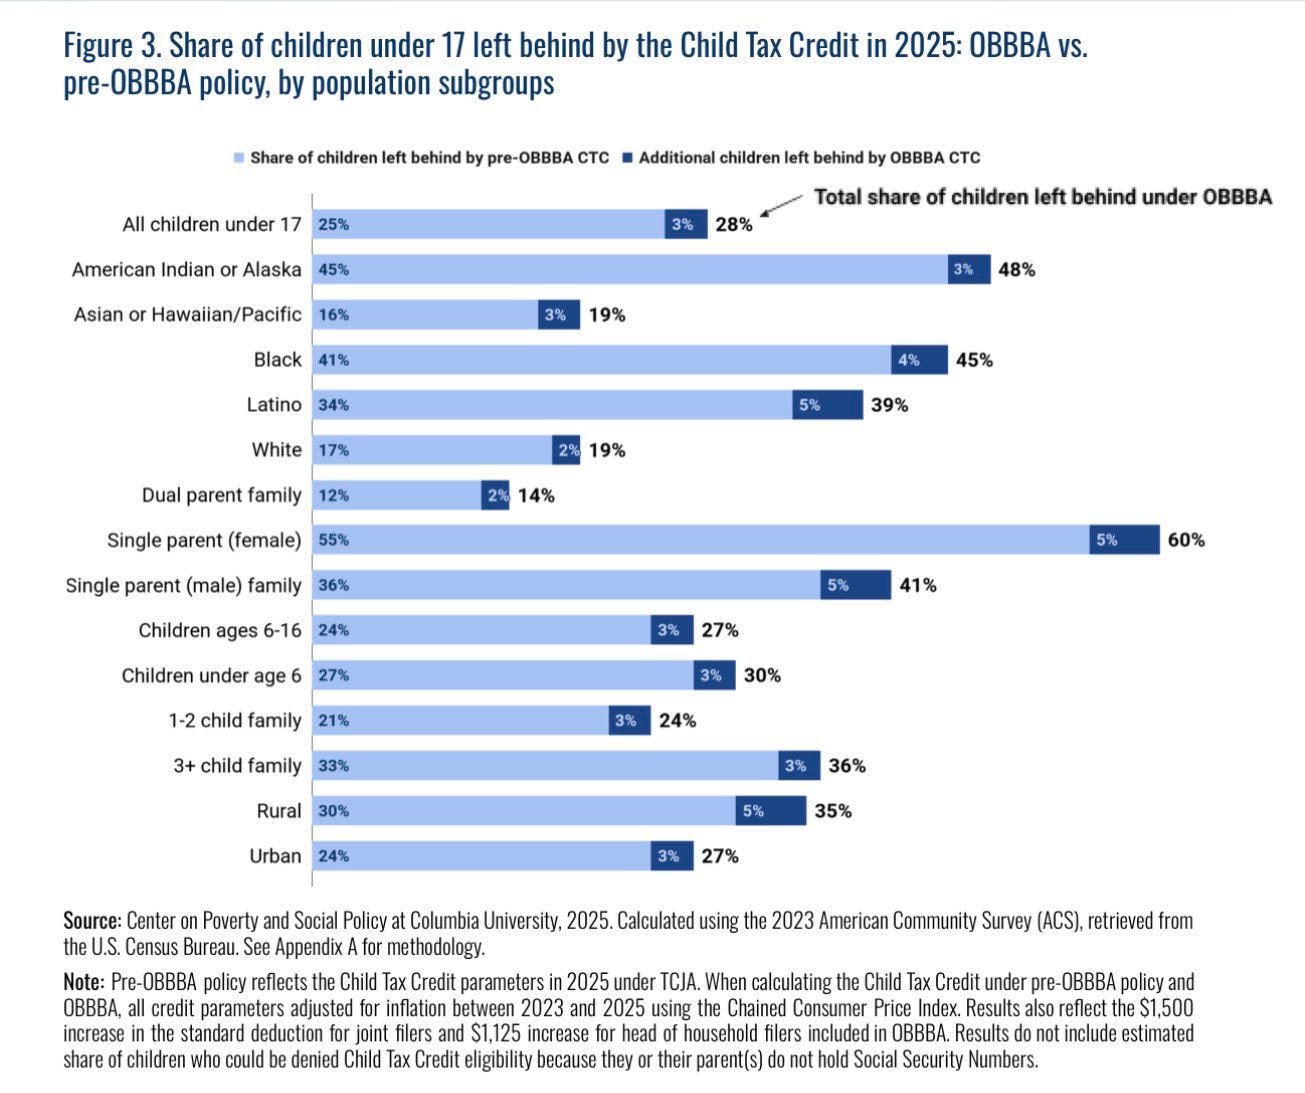
That national number, however, hides enormous variation by family type. Children in single-mother households are left behind at more than four times the rate of children in dual-parent households: 60% and 14%, respectively.
That gap dwarfs every other disparity in the same dataset, which also documents disparities for babies and young children, children of color, rural children, and larger families — each reflecting serious equity problems in their own right.
CPSP also finds the harm to children is concentrated geographically.3
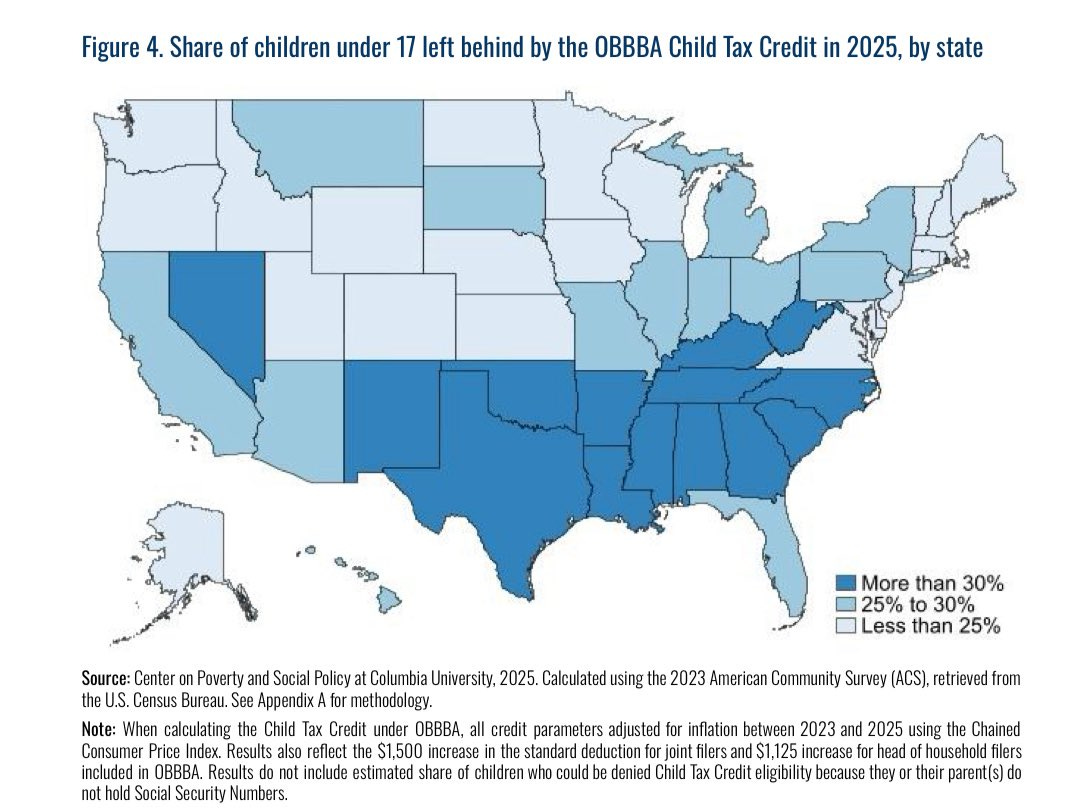
The design of the Child Tax Credit, in effect, punishes roughly 19 million children because of their household conditions. The kids most in need get the least under this policy.
In addition to the children from demographic groups, because the credit is pegged to a single tax year’s earned income, kids are punished for circumstances far outside their control, including:
Having a mother who loses income during pregnancy, childbirth, and postpartum, so no longer qualifies for the full credit for their baby and the baby’s siblings.
Living through a natural disaster with an accompanying loss of household income
Experiencing the death of a parent.
Suffering as a victim of violence or abuse and a related loss of household income.
Dealing with a parent who suffers from an illness, such as cancer, or has a disability that reduces household income.
Having a parent serve as a caregiver for a child, their other parent, or other family member.
Living with a parent who loses a job and income, even on a temporary basis.
These points are often lost in family-structure debates that focus on parenting behavior as the reason for higher rates of child poverty, rather than on other factors, including government’s own policy design.
The Mechanism: A Phase-In That Favors Two-Earner Households, and Punishes Moms and Babies
Under current law, the Additional Child Tax Credit — the refundable portion of the credit — phases in at 15% of earnings above $2,500. A household needs substantial earned income before it can claim the full credit, and the income threshold rises steeply with each additional child.
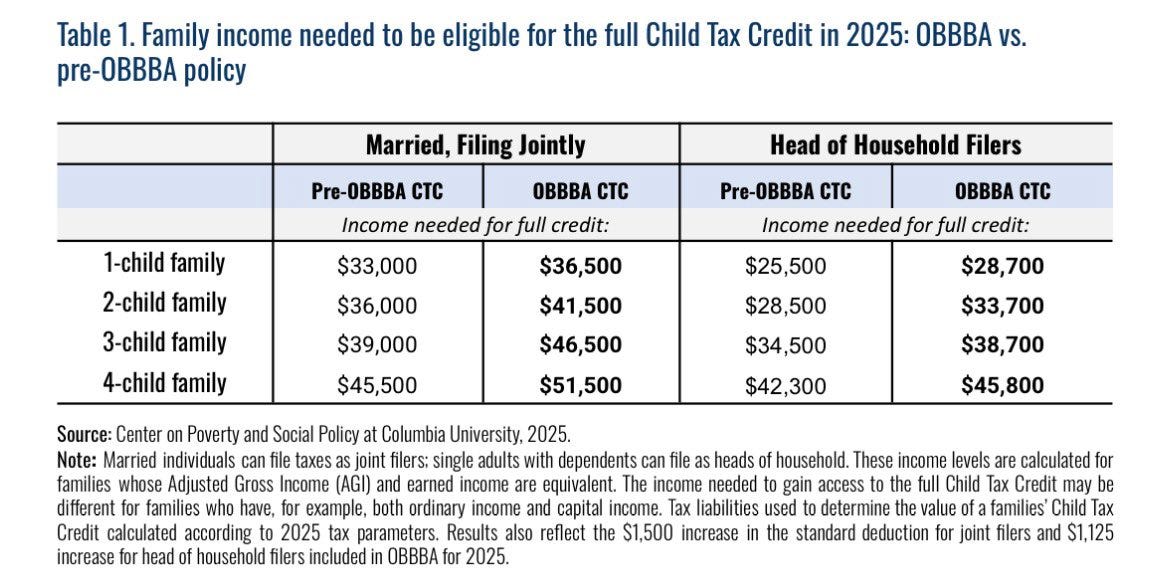
According to CPSP, a head-of-household filer with one child now needs $28,700 in earnings to receive the full credit under OBBB — up from $25,500 under prior law. A filer with two children needs $33,700, up from $28,500. And a single parent with four children must now earn $45,800 to receive the full credit, up from $42,300.
Compounded with the fact that mothers lose income during pregnancy, childbirth, and the postpartum period, families with newborns are often subjected to a “double penalty”:
The loss of income associated with the birth of a child.
The higher earnings threshold required to qualify for the full credit.
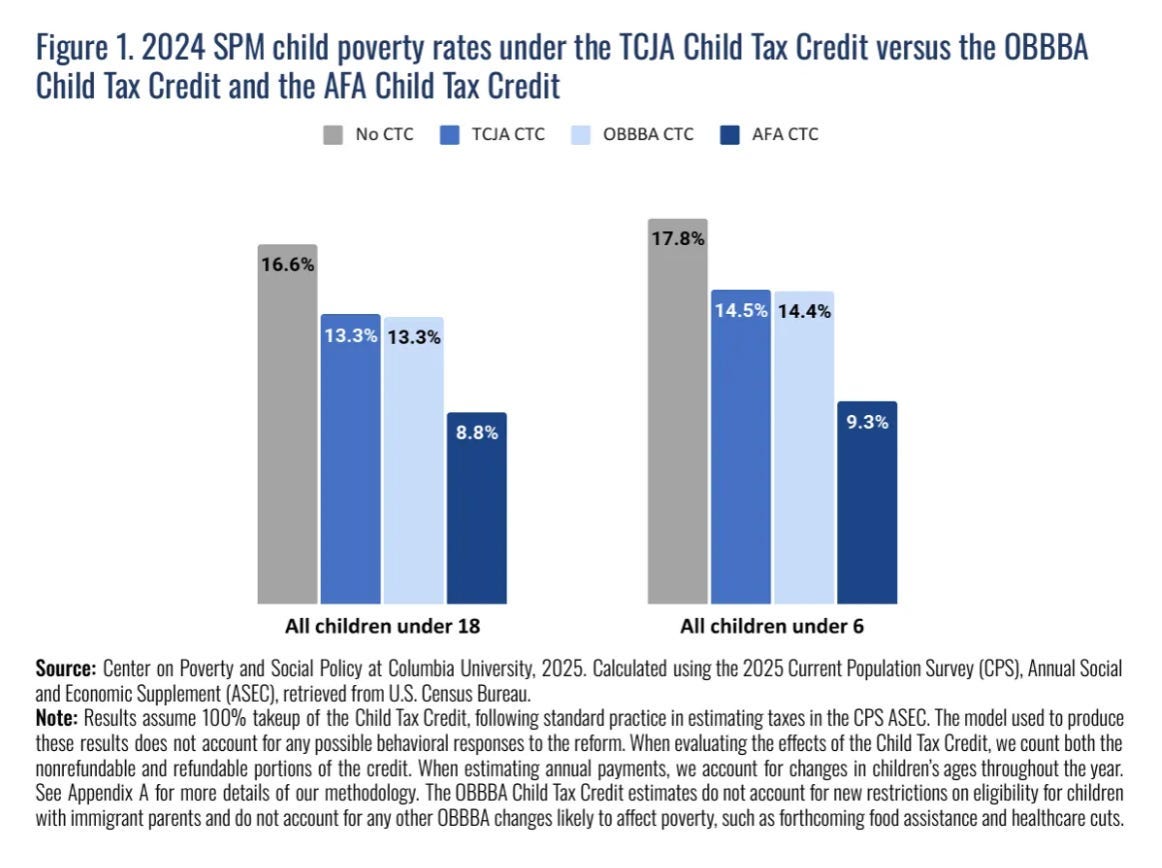
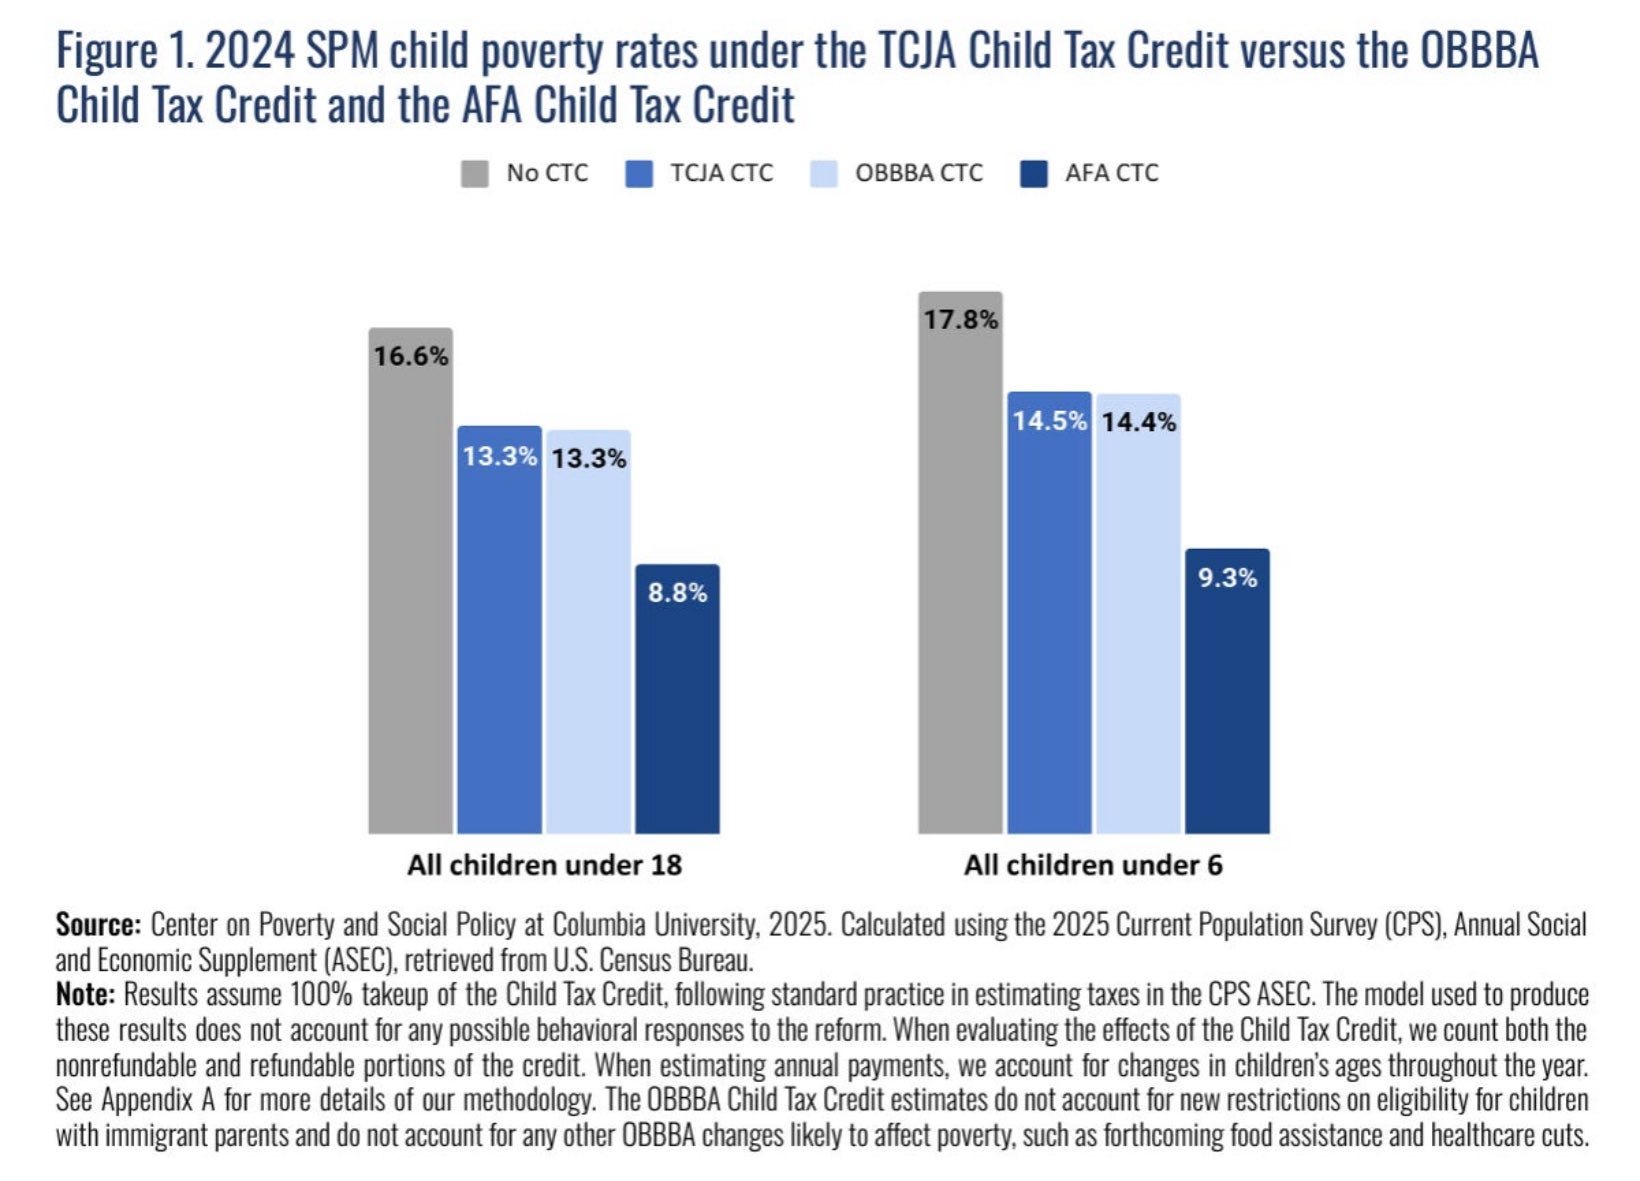
This helps explain why younger children and children in larger families are disproportionately left behind by the Child Tax Credit, and why there are higher poverty rates among children in those families. The following chart by CPSP shows the impact on child poverty if there were no CTC (grey bar), the CTC before passage of OBBB (royal blue), the CTC after passage of OBBB (light blue), and if the CTC were expanded and made fully refundable, as through the American Family Act (navy blue).
This gap between eligibility and need doesn’t happen by necessity. Child poverty is a policy choice. It reflects a specific design choice, as the international comparison below shows — countries that don’t attach eligibility to earnings don’t produce this disparity at all.
For single-parent households, the credit’s phase-in creates a structural bind two-parent households don’t face: a married couple can split the labor needed to reach the income threshold across two adults — each working a manageable, caregiving-compatible number of hours while the other covers child care. A single parent has to clear the same bar entirely alone, with no second adult to add income and no second adult to care for the kids while they work.
Take two households earning the same $15-per-hour wage. A married couple with two kids, each working 30 hours a week and trading off childcare between them, brings in $46,800 combined — comfortably above their $41,500 threshold, without either parent working full-time-plus hours. A single parent with two kids, working that same reasonable 30-hour week, brings in $23,400 — well short of the $33,700 they’d need, because there’s no second income to stack on top. To close that gap alone, they’d need roughly 43 hours a week, every week, while also being the only adult available to arrange and pay for child care during those hours.
That last point regarding child care compounds the problem. Single parents typically face higher child care costs relative to income than two-parent households, precisely because there’s no second adult available to cover care for free while the other works. The economies of scale a married household gets from splitting earning and caregiving between two people simply aren’t available in the same way to a household with one adult.
Extended family support (when available) can partly substitute for a second parent’s flexibility, but single parents are also less likely to have that backup nearby as well. The credit’s phase-in effectively assumes every household can flex a second adult’s hours to clear the threshold. Only two-parent households can do that.
The Paradox: Raising the Credit Amount Made This Worse
For those who assume a bigger credit is automatically a better credit, OBBB’s increase in the maximum Child Tax Credit per child from $2,000 to $2,200 failed to even keep pace with past levels of the CTC in 2004, 2017, and 2021.
Even worse, because the increase didn’t come with any change to the phase-in or refundability rules, raising the credit amount without fixing refundability increased the number of children left behind by three million children — again, from 25% under prior law to 28% under OBBB.4
Every dollar added to the credit’s ceiling, without mechanically addressing refundability, widens the gap between “eligible” and “excluded.” This has been a design choice: a policy sold as an expansion that functioned, for the children in families with the least income, as a bigger gap.
What a Fix Looks Like
The American Family Act (AFA), reintroduced by Reps. Rosa DeLauro (D-CT), Suzan DelBene (D-WA), and Ritchie Torres (D-NY), and Sens. Michael Bennet (D-CO), Cory Booker (D-NJ), Raphael Warnock (D-GA), Catherine Cortez Masto (D-NV), Dick Durbin (D-IL), and Ron Wyden (D-OR) and included temporarily as part of the Child Tax Credit in 2021 after passage of the American Rescue Plan Act (ARPA), would make the credit fully refundable. Every eligible child receives the credit regardless of how much their parent earned, and the credit would be paid monthly rather than as an annual lump sum at tax time.
The differences are profound and highly important to millions of children.
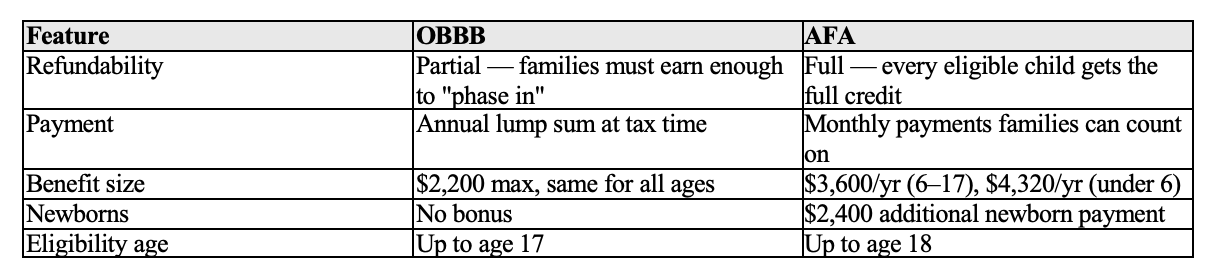
The poverty-reduction difference is large. CPSP’s modeling puts child poverty at 13.3% under OBBB versus 8.8% under the AFA for all children under 185, and the gap is even larger for poor children under six, precisely the group where family income instability does the most developmental harm, and for children living in single-parent households.
Full refundability also changes who the benefit reaches. The Institute on Taxation and Economic Policy (ITEP) shows the average benefit for the bottom 20% of earners jumping from $200 under OBBBA to $4,900 under the AFA — a 24-fold increase concentrated exactly where the phase-in currently excludes families.6
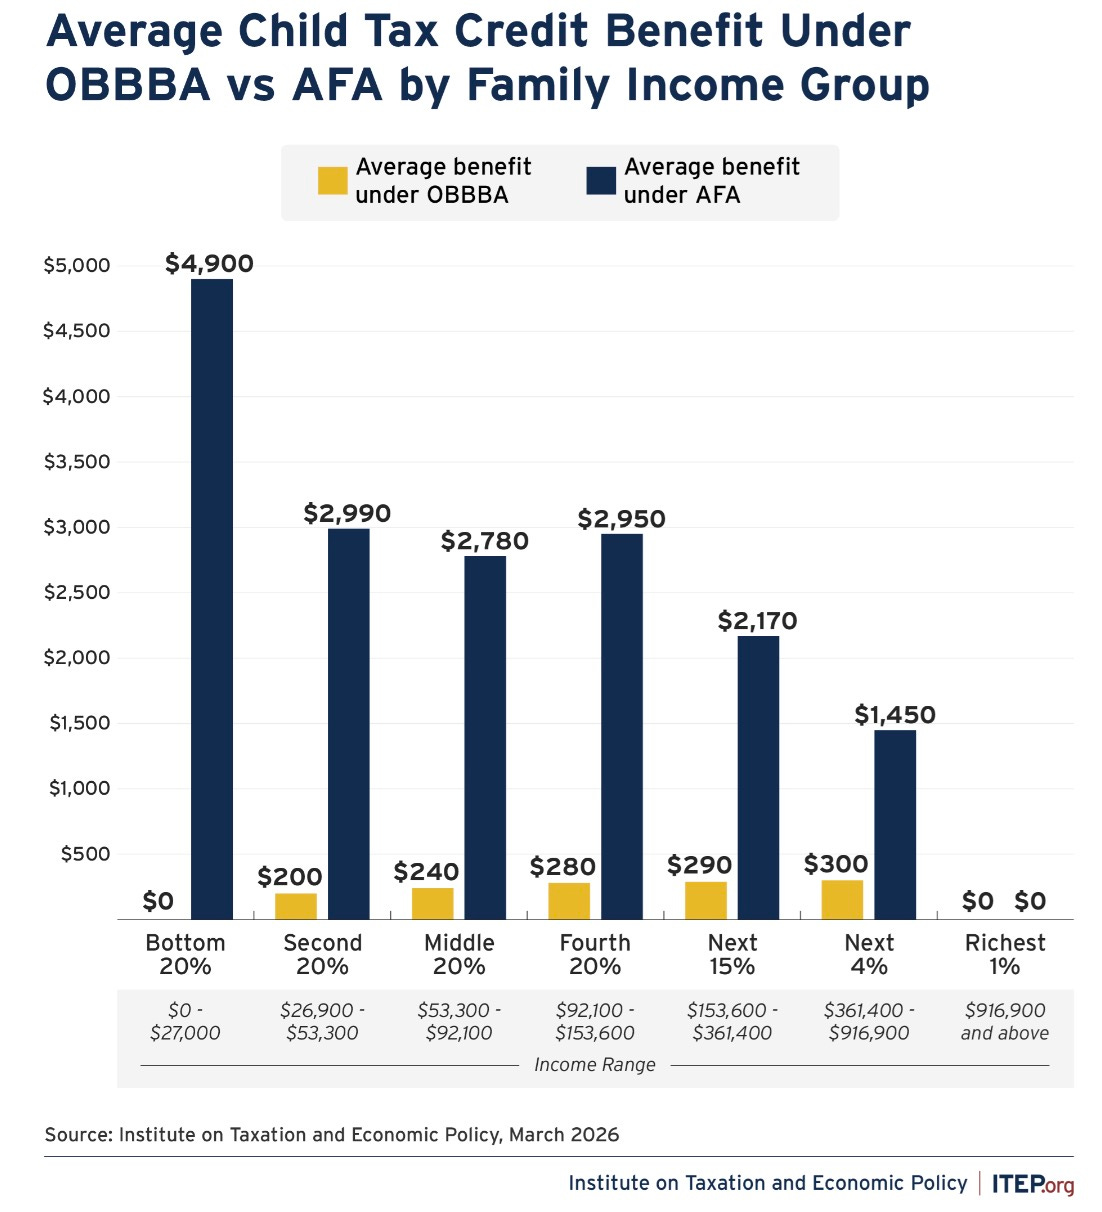
Notably, families in the second through fourth income quintiles still see roughly $2,800–$3,000 average benefits under the AFA, meaning the reform is not a zero-sum shift. Instead, it reaches all kids, including those at the bottom, without hollowing out the middle.
A Different Way of Thinking About Support for Children
This past spring, First Focus on Children asked a team of University of Maryland School of Public Policy students to examine how best to reduce child poverty in single-parent households. They chose to compare U.S. policy to that of other countries.7
Their analysis found the following about the U.S. Child Tax Credit:
. . .the CTC’s effectiveness in alleviating poverty among single parents is limited by these policies, which undermine equity and create a complex set of rules that complicate the administrative feasibility of calculating the appropriate benefit.8
Their conclusion was that countries with much lower child poverty rates begin with a common premise: child benefits are designed to provide stable support for children rather than requiring parents to meet “deservingness” standards related to work, marriage, immigration status, disability, or earnings.
Their work shows the same underlying fix from the Nordic countries holds up across all three designs.
Norway: Supporting Families During the Earliest Years
The students highlighted Norway’s parental benefit system because it addresses one of the biggest weaknesses in the American Child Tax Credit: the period immediately following a child’s birth, when family income often falls even as expenses rise.
Under Norway’s model, eligible parents receive paid parental leave with income replacement after the birth of a child. Parents who qualify may take roughly a year of leave, much of it paid, with portions reserved for mothers, fathers or co-parents, and the remainder shared between them. Parents may also use portions of the leave flexibly before a child turns three. Those who do not qualify for paid leave receive a one-time benefit instead.
The students argued that this approach reduces one of the structural disadvantages facing single-parent households. Rather than conditioning support on reaching higher earnings after a child is born, as the U.S. Child Tax Credit effectively does through its refundability rules, Norway provides income support during precisely the period when caregiving responsibilities are greatest.
Sweden: Every Child Receives the Benefit
Of the three countries studied, Sweden offers perhaps the clearest contrast with the American Child Tax Credit.
The students focused on Sweden’s universal child allowance (Barnbidrag system), which provides a flat monthly benefit to families regardless of income or employment status. Single custodial parents receive the full benefit without a marriage penalty, and eligibility does not depend on earned income or tax liability. The benefit is paid automatically rather than requiring families to navigate a complicated refundability formula.
The students also examined research showing that directing the allowance by default to mothers increased the share of resources reaching separated and low-income mothers without reducing labor-force participation. Their broader conclusion was that predictable, universal benefits can strengthen the economic stability of single-parent households while avoiding many of the administrative barriers and penalties built into the U.S. Child Tax Credit.
Denmark: Making Work Possible
While Norway emphasizes parental leave and Sweden emphasizes universal cash benefits, Denmark combines income support with policies designed to help parents remain connected to the workforce.
The students highlighted Denmark’s “flexicurity” model, which pairs family benefits with subsidized childcare, active labor-market programs, and employment supports. Rather than treating cash assistance and work as competing goals, Denmark seeks to make employment feasible for parents by reducing child care costs and investing in workforce participation.
One finding particularly relevant to single-parent households was Denmark’s emphasis on affordable child care. The students noted evidence that Danish single parents face substantially lower childcare costs relative to income than families in countries with less comprehensive childcare systems, making it easier to maintain employment while raising children. They also pointed to Denmark’s strong labor-force participation among single mothers as evidence that universal family supports and employment need not be competing objectives.
What the Students Ultimately Recommended
Perhaps the most interesting conclusion from the students’ work was that they did not recommend importing any one country’s system wholesale.
Instead, they recommended combining elements of Sweden’s universal child allowance with Denmark’s investments in child care and employment supports. Their proposal recognized that reducing child poverty requires more than a single policy. Stable income support, affordable child care, and opportunities for parents to work reinforce one another.
The same lesson applies to the Child Tax Credit. Whether Congress adopts the broader vision the students proposed or simply reforms refundability through the American Family Act, the underlying principle is the same: eligibility should begin with the child and not with whether a parent earns enough to satisfy an arbitrary threshold.
They recommend:
Provide guaranteed monthly financial support to all families with children, regardless of income or employment status, to reduce poverty and improve long-term economic stability for single-parent households.
Reduce the administrative burden by implementing a universal parental benefit that begins at birth and ends at age 18.9
Their work is a reminder that some of the most valuable policy ideas come from asking fresh questions and from beginning with the needs and best-interests of children rather than ideology. They didn’t ask which families deserved help. They asked how public policy could better ensure that children in every family, regardless of composition or household status, had a fair chance to succeed.
The Bottom Line
When we think about child poverty, our priority should be to lift up every child to help them flourish and thrive rather than to punish them for the circumstances of their parents related to marriage, work, immigration status, disability, or earnings.
Unfortunately, as currently constructed, the Child Tax Credit amplifies disparities and actually pushes millions of children into poverty. Congress can change that.
Children in single-parent households don’t need judgment or blame and shame policies. They need structures and supports that recognize their inherent worth and invest in them.
ENDNOTES
Kreitzer, R.J. and Watts Smith, C. (2018). Reproducible and Replicable: An Empirical Assessment of the Social Construction of Politically Relevant Target Groups. PS: Political Science and Politics. 51:4. 768-774.
Collyer, S., et al. (2025, Aug. 6). Children Left Behind by the H.R.1 “One Big Beautiful Bill Act” Child Tax Credit. Center on Poverty and Social Policy (CPSP), Columbia University. Poverty and Social Policy Brief. 9:5.
CPSP. (2025, Aug. 6); see also, Lesley, B. (Jul 1, 2026). Children Are Increasing in the South: Their Champions Aren’t. Substack. https://brucelesley.substack.com/p/children-are-increasing-in-the-south.
Ibid.
Ibid.
Hughes, J. (2026, Mar. 10). The Child Tax Credit Leaves Out Millions of Children in 2026. There Are Better Alternatives. Institute on Taxation and Economic Policy (ITEP). https://itep.org/child-tax-credit-2026-obbba-trump-taxes/.
Lumpkin, K., Molina, P., Neubauer, G. & Rodriguez, J. (2026, Apr. 27). Final Policy Brief and Memoranda on Child Tax Credit Alternatives. University of Maryland School of Public Policy, prepared for First Focus on Children.
Ibid.
Ibid.